UN Warns Global Economic Growth Will Slow to 2.6% in 2026

Shibbir Ahmed, New York — The United Nations has warned that global economic growth is expected to slow to 2.6% in 2026, down from 2.9% in 2025, as escalating tensions in the Middle East, rising energy costs and growing uncertainty in international trade put pressure on the world economy.

According to the United Nations Conference on Trade and Development (UNCTAD), the latest economic outlook highlights the vulnerability of developing economies to geopolitical shocks and rising import costs. The agency cautions that the effects of the Middle East crisis are extending beyond the region, affecting energy markets, business confidence and the broader outlook for global trade.

The report comes at a time when governments and businesses are confronting a combination of geopolitical instability, inflationary pressures and changing international economic relationships.

The conflict in the Middle East has intensified concerns about global energy supplies, particularly as uncertainty surrounding oil production and shipping routes threatens to increase costs for businesses and consumers.

Higher energy prices can affect transportation, manufacturing, electricity generation and food distribution, creating additional pressure on household budgets and business operating expenses. Countries that rely heavily on imported fuel are particularly exposed, as rising import bills can weaken their financial positions and increase inflationary pressures.

UNCTAD’s assessment indicates that geopolitical instability is becoming an increasingly important factor in the global economic outlook. Continued uncertainty could discourage investment, disrupt supply chains and limit the ability of governments to support economic activity.

Developing Economies Face Growing Pressure
Developing countries are expected to experience uneven economic conditions as higher energy costs combine with existing financial challenges. Nations dependent on imported fuel and external borrowing could face greater difficulties financing infrastructure, public services and industrial development.

UNCTAD projects growth in developing economies at 4% in 2026, compared with 4.7% in 2025. Although the projected rate remains above the global average, the slowdown highlights the difficulties facing countries attempting to sustain economic expansion amid volatile international conditions.

The agency has also raised concerns about unequal access to investment, technology and higher-value industries. Economies with limited industrial capacity may struggle to capture the benefits of global trade and technological advances, widening existing development gaps.

International trade continues to provide opportunities for economic expansion, but shifting geopolitical relationships and changing supply chains are creating new challenges for businesses.

Demand for semiconductors, advanced computing equipment and artificial intelligence infrastructure has supported activity in parts of the global economy. However, UNCTAD warns that the benefits of technological investment remain concentrated in a relatively small number of economies and companies.

For countries seeking sustainable growth, strengthening domestic industries, improving access to technology and diversifying export markets will remain important priorities. The UN’s forecast underscores the uncertainty facing the world economy as policymakers respond to energy market volatility, geopolitical tensions and changing trade patterns.

The direction of oil prices, the security of major shipping routes and the progress of diplomatic efforts in the Middle East will be important factors influencing economic conditions in the coming months. While the global economy is still projected to expand in 2026, the lower growth forecast signals that countries may face a more difficult environment for investment, job creation and improvements in living standards.

The UNCTAD assessment reinforces the importance of international cooperation, resilient supply chains and policies that help vulnerable economies withstand external shocks.


Landau Calls for Shift From Aid to Investment in U.S. Economic Diplomacy

Shibbir Ahmed, New York — U.S. Deputy Secretary of State Christopher Landau has called for a stronger focus on trade and private investment as a long-term alternative to traditional foreign aid, saying economic diplomacy should play a central role in strengthening relationships between countries. Speaking at a Trade Over Aid Deals Showcase on September 25, Landau said economic and commercial issues had for decades taken a back seat in diplomacy, which he argued had too often focused primarily on political, military and security matters.

‘Economic and commercial issues should be treated as a core element of diplomacy’, Landau said, arguing that governments have a responsibility to create prosperity, economic opportunities and jobs for their people. Landau said economic projects can create lasting relationships that survive changes in government. While acknowledging that aid programs can help countries remain afloat, he argued that long-term economic projects can provide more sustainable value by generating investment, infrastructure, employment and economic growth.

He also emphasized that foreign investment does not necessarily mean a loss of national sovereignty. According to Landau, governments should establish clear terms and conditions for investments so that both investors and host countries understand their respective obligations and potential returns.

‘Investment is an engine of growth’, Landau said, urging governments and businesses to view foreign capital as an opportunity to expand economic activity rather than as a threat to sovereignty. He described investment relationships as potentially “win-win” arrangements, saying capital inflows can support infrastructure, jobs and economic growth while also strengthening political and commercial ties between countries.

U.S. private sector at the center

Landau said one of his priorities as deputy secretary is to improve communication between the U.S. government and American companies seeking investment opportunities overseas. He noted that during trips around the world, he frequently hears foreign governments asking why American companies are absent from projects where businesses from other countries have submitted bids.

Landau said he had previously focused largely on American companies directly operating overseas, including construction, infrastructure, oil and mining firms. He said he now sees a greater role for U.S. financial capital, particularly from New York City, which he described as the world’s financial capital.

‘There are trillions of dollars here that can be deployed around the world,’ Landau said, arguing that attracting capital providers could help connect foreign investment opportunities with American operating companies. He said he recently met with major capital providers to discuss why they were not investing in certain countries and what obstacles were preventing greater U.S. participation.

Calls for a more coordinated U.S. approach

Landau also acknowledged concerns from private investors about the fragmented nature of the U.S. government’s economic engagement overseas. He said investors sometimes want the U.S. government to have a financial stake or other involvement in projects to reduce risks associated with political changes in foreign countries.

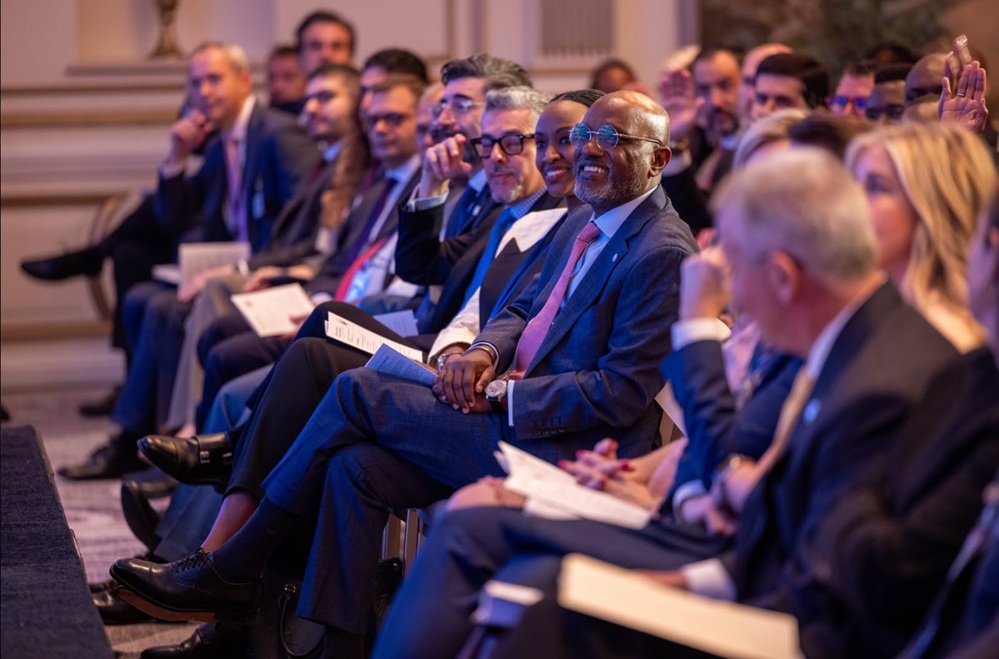
Government officials, private-sector representatives and international participants attend the “Trade Over Aid Deals Showcase” as U.S. officials discuss expanding trade and investment opportunities.

Landau said he wants the State Department, Commerce Department, Export-Import Bank, Development Finance Corporation and Millennium Challenge Corporation to work more closely together and make the U.S. government a more accessible “one-stop shop” for businesses seeking to invest overseas.

He cited the Pacific Islands as one region where he believes greater investment opportunities exist. Landau said he had organized a business summit and investment roundtable in Honolulu in February with Pacific Island leaders and U.S. private-sector representatives to identify sectors where investment could be expanded.

Landau said the U.S. government’s role is to improve communication between governments, businesses and investors and help identify opportunities for private capital. Concluding his remarks, Landau reaffirmed his commitment to expanding the global role of American businesses and called for what he described as an “unprecedented golden era for the American private sector around the world.”


Canada Escalates Trade Fight With New Tariffs on U.S. Goods

Shibbir Ahmed, New York: Canada is escalating its trade fight with the United States, announcing new retaliatory tariffs of up to 50 percent on hundreds of American products as tensions between the two longtime allies continue to worsen.

The Canadian government said Tuesday that the new measures will target approximately $20 billion worth of U.S. imports and will take effect on September 8. The tariffs are being imposed in response to new U.S. tariffs on Canadian goods that took effect after trade negotiations between the two countries broke down.

The Canadian counter-tariffs will range from 15 percent to 50 percent, depending on the product. Items affected include steel, aluminum, dairy products, seafood, furniture, clothing, electronics, machinery and other American-made goods.

Canada strikes back

The move represents a significant escalation in the dispute between Washington and Ottawa. The United States recently imposed a 50 percent tariff on $27.6 billion of Canadian goods, effective August 22. Canada said its response was designed to match the value of the new American measures while protecting Canadian businesses and workers.

Canadian Finance Minister François-Philippe Champagne said the government is taking targeted action while providing support to companies and workers affected by the trade conflict. Canada has also announced measures to help businesses maintain liquidity and adjust to the changing trade environment.

Hundreds of U.S. products targeted

According to the Canadian government, the new tariffs will cover products selected from categories targeted by recent U.S. trade measures. The rates will be 15 percent, 25 percent or 50 percent, depending on the product. The measures are expected to affect about 4.5 percent of Canada’s imports from the United States, based on 2024 trade figures.

Canadian officials say the government wants to protect domestic industries while keeping pressure on Washington to reconsider its tariff policies. The government has also introduced a support package for Canadian businesses and workers affected by the dispute, including financial assistance intended to help companies manage higher costs and disruptions to supply chains.

Growing economic pressure

The escalating tariff battle threatens to raise costs for businesses and consumers on both sides of the border. American industries that rely heavily on the Canadian market could face reduced exports, while Canadian companies dependent on U.S. goods may encounter higher costs. Economists have also warned that prolonged tariffs could disrupt North American supply chains and increase prices.

The dispute is particularly significant because Canada and the United States maintain one of the world’s largest bilateral trading relationships. The latest escalation comes as President Donald Trump continues to criticize Canada over trade and other political issues. Trump has also threatened additional tariffs on Canadian automobiles, adding to uncertainty for manufacturers and workers on both sides of the border.

Relations reach a new low

The latest tariff measures come after negotiations between Washington and Ottawa failed to produce an agreement. Canadian Prime Minister Mark Carney has indicated that Canada remains willing to return to negotiations, but Ottawa has also made clear that it is prepared to defend Canadian economic interests.

The worsening dispute has created uncertainty for businesses, farmers, manufacturers and exporters throughout North America. With Canada’s new tariffs scheduled to take effect September 8, pressure is now building on both governments to find a way to prevent the trade conflict from becoming even more damaging. The latest measures mark another major step in the deepening U.S.-Canada trade dispute and raise fresh concerns about prices, jobs and supply chains across North America.